Megan Casebier

Case study · Obie, 2025–26 · 6 min read

Homeowners ran on a platform built for landlords, so every seam was ours to hide

This is the story of Obie’s first homeowners line: a different product, for a different user, on a backend that had never contemplated it—and of the seams we didn’t hide until agents found them.

Role
Senior Product Designer
Timeline
4 months (Dec ’25 – Apr ’26)
Surface
Agent quoting platform
Status
Bind-ready April 29, 2026

Homeowners shares almost nothing with landlord

Obie built its business on insurance for landlords and real estate investors, and was acquired by The Baldwin Group (NASDAQ: BWIN). Then leadership set a mandate: expand into homeowners insurance by April.

That sounds like a feature. It isn’t. Homeowners has different carriers, different underwriting models and different risk profiles, and the person doing the work changes too: landlord was a simpler, consumer-facing, self-serve flow; homeowners is professional agent work. Insurance scoring, which homeowners requires, was brand new to Obie.

The bar was bind-ready on day one: real agents generating real quotes that produced real policies. Under it sat a landlord-era backend and a set of hard constraints. Carrier rates came from live API calls tied to risk-profile changes. The rater couldn’t take a ping on every keystroke. Validation rules varied by package type. And homeowners was only the first expansion, so whatever we built had to take the next carrier without a redesign.

Rebuilding the backend was off the table with an April deadline. Every gap between what the platform assumed and what homeowners needed would have to be closed in the interface, or show up in front of an agent.

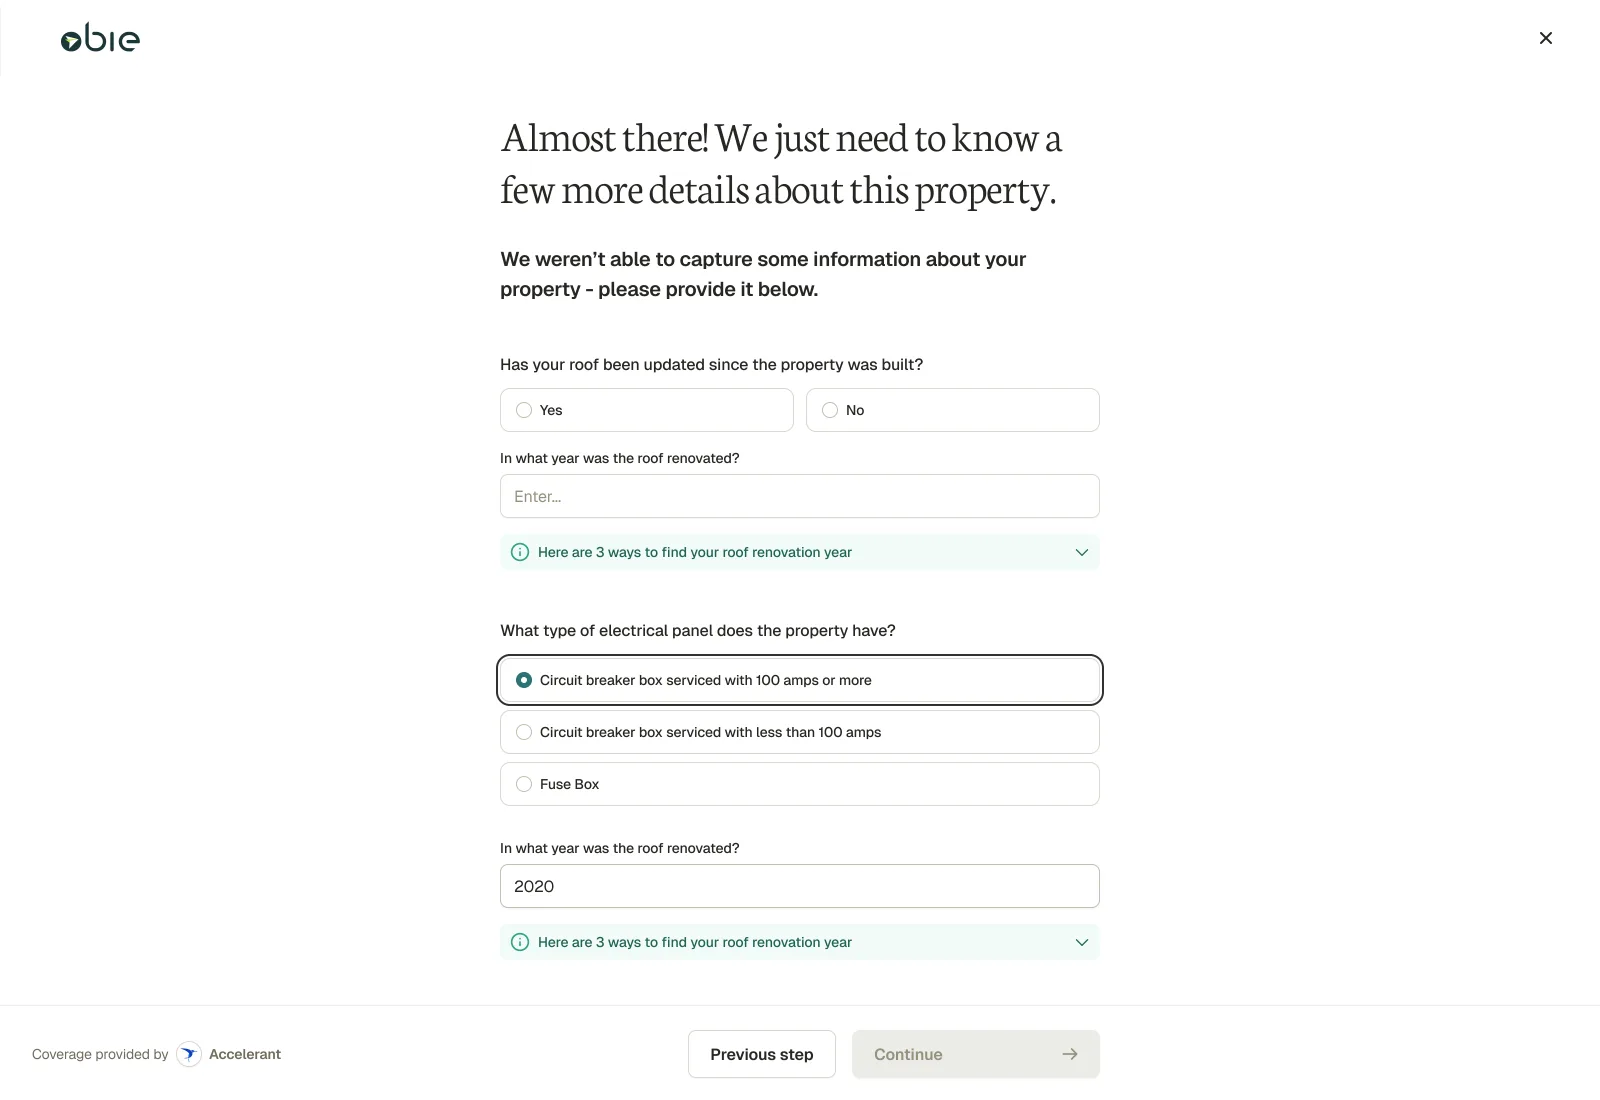
Before: the consumer landlord flow asking a few follow-up property questions, roof renovation year and electrical panel type, one screen at a time
Before: a landlord, self-serve, a few questions a screen.
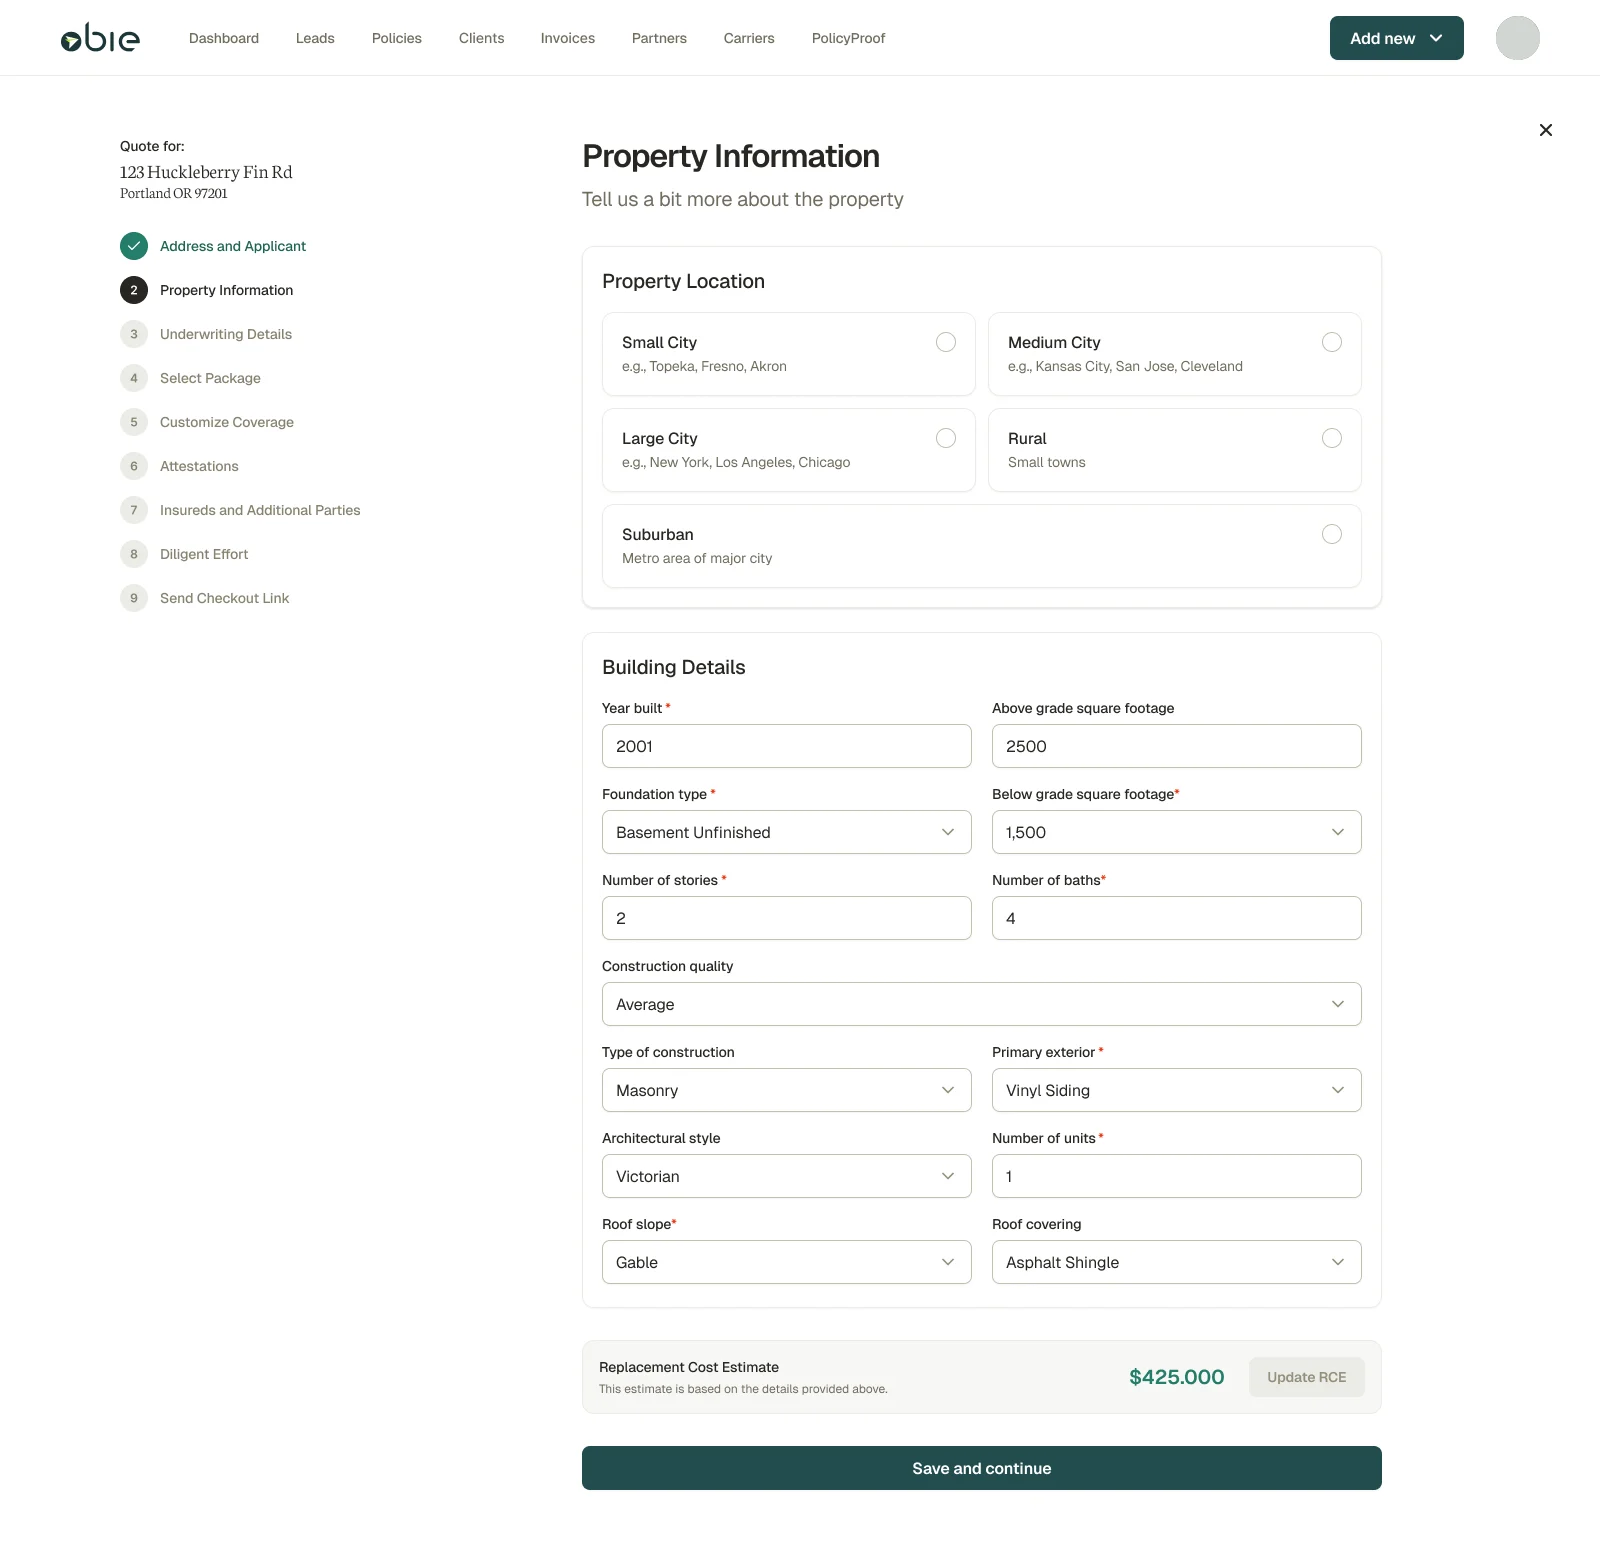
After: the agent homeowners flow, Property Information step, with a nine-step progress list, property location choices, building details and a replacement cost estimate
After: an agent, with all nine steps in view.
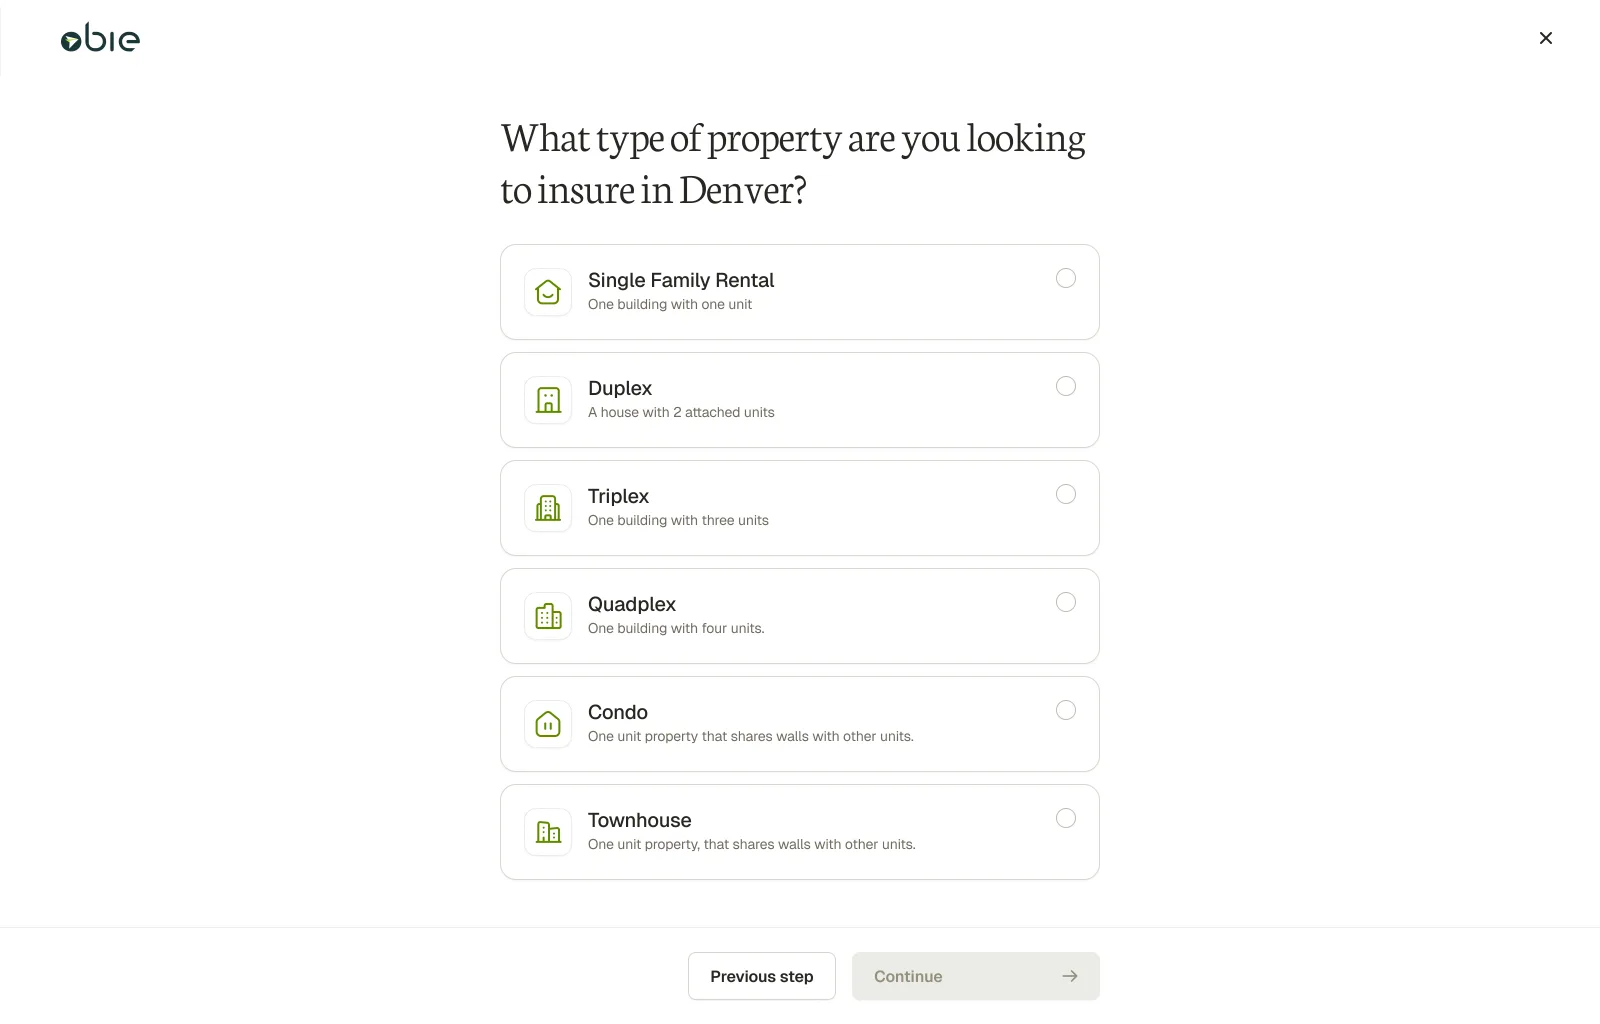
Before: the consumer landlord flow asking what type of rental property to insure, from single family to townhouse
Before, the underwriting: what kind of rental is it?
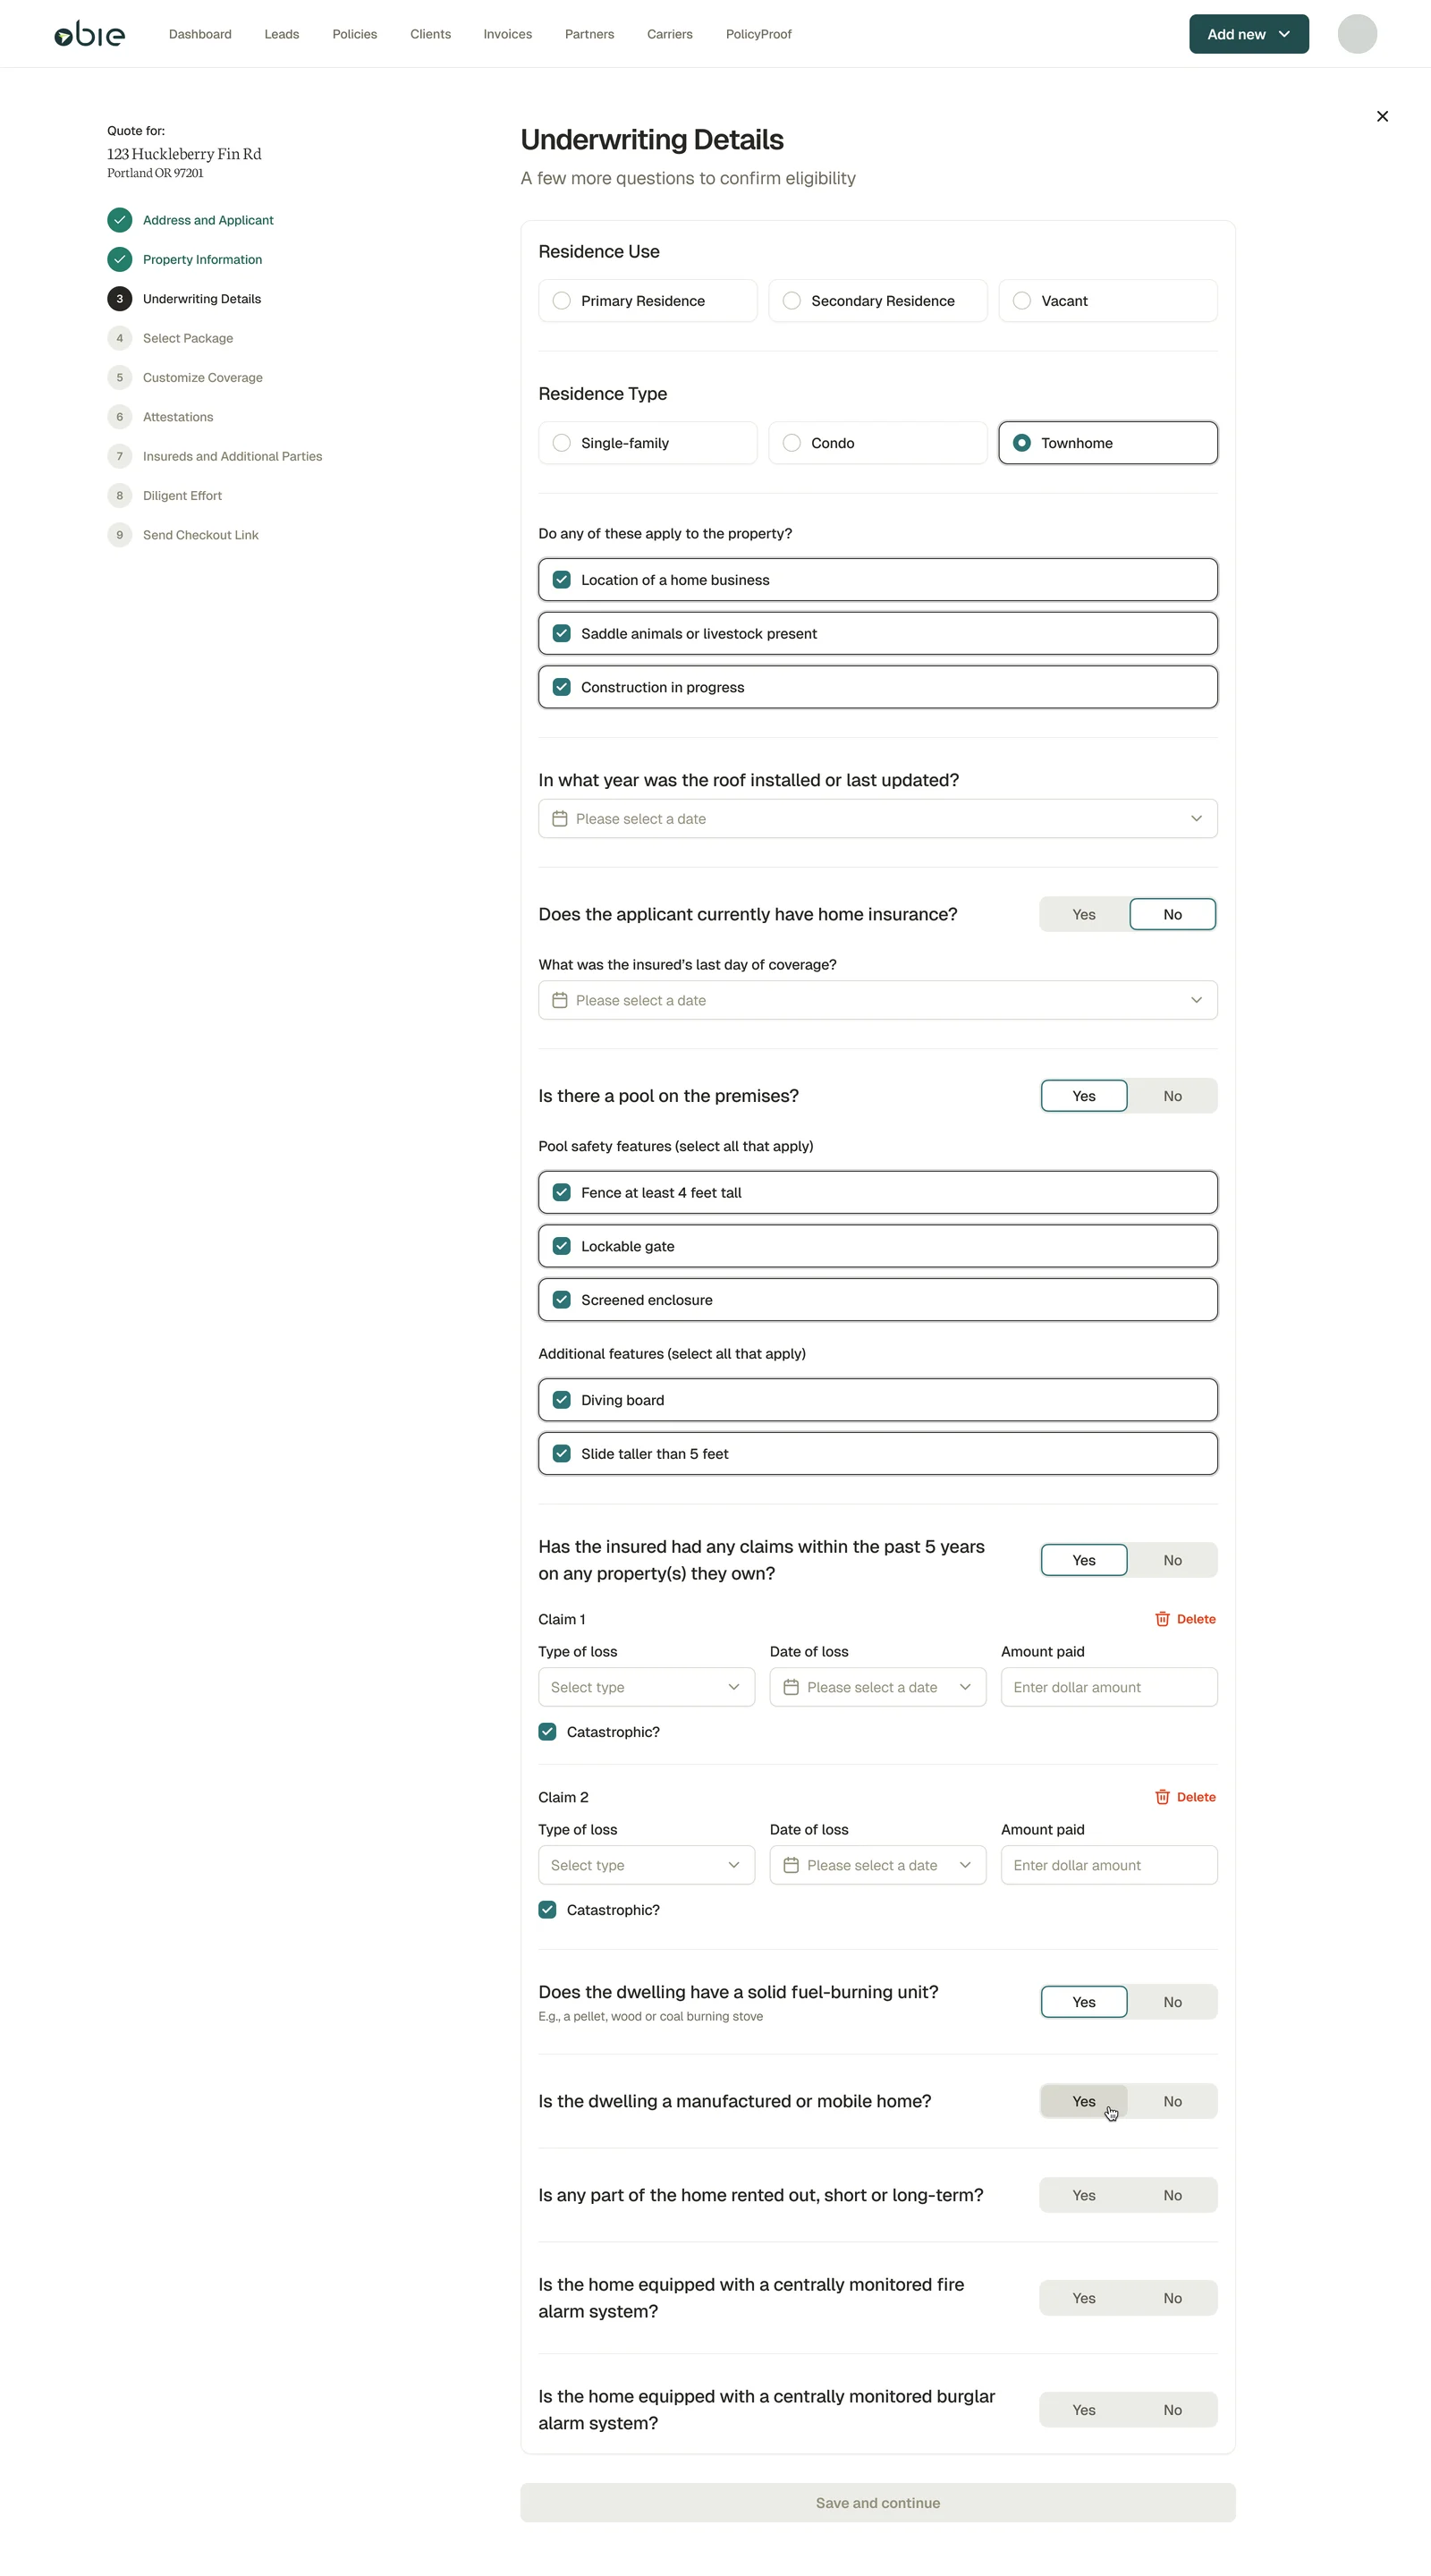
After: the agent Underwriting Details step, with residence use and type, property risk checkboxes, roof year, prior insurance, pool safety features, prior claims and other eligibility questions
After: the question set Underwriting signed off on, package by package. Almost nothing carried over.

Two bets, both against a rewrite

Both decisions had to be made early, and both were the same bet in different clothes: make the old platform carry the new product, and pay for it somewhere the agent would never see. Reversing either one mid-build would have cost the April date.

Identity edits after insurance scoring

The backend assumed identity data never changed once a score existed. Agents routinely correct it mid-quote.

The tension

Scores required PII and couldn’t be recalculated arbitrarily. The landlord-era backend assumed identity data wouldn’t change after scoring. But agents routinely discover corrections in the middle of a quote, and locking the fields would break their workflow.

Options evaluated

  • Lock identity fields after scoring — breaks agent workflows
  • Re-score on applicant changes only, before bind — requires backend coordination
  • Recalculate score on every change — compliance and performance risk
  • Rebuild client infrastructure — ideal, but out of MVP scope

The price

The ideal answer, rebuilding the client infrastructure, was the one we couldn’t afford. The April deadline ruled it out. Editing the named insured doesn’t re-run the score; changing the applicant does, on purpose.

What it bought

It bridged the old backend and the new product without a rewrite, and it became the pattern for every later case where homeowners needed something the existing infrastructure didn’t natively support. One answer, reused.
Package switching mid-flow (HO-3 ↔ HO-5 ↔ HO-6)

Agents compare packages while the client is still talking. The flow has to keep up.

The tension

HO-5 requires substantially more underwriting questions than HO-3, with only a minority universal across packages. Restarting the flow would mean re-entering substantial data. The easy path was to lock package selection early, and it would have broken the agent workflow and created technical debt for every future carrier.

Options evaluated

  • Lock package once chosen — simplest, broke agent workflows
  • Allow switching with full reset — agents re-enter everything
  • Switch freely; shared answers carry over — best for agents, hardest to build

The price

We picked the hardest option to build. Shared answers had to port automatically, only the new package’s questions could surface, and switching back had to leave the original quote exactly as it was.

What a switch has to promise: answer only what’s new, and lose nothing on the way back.
  1. Agent starts with

    HO-3

    Complete quote in progress

  2. Universal data carries over

    Shared questions port automatically

  3. Only new questions surface

    HO-5 specific requirements

  4. Switch back anytime

    no loss

    Original quote preserved

What it bought

Agents could compare packages in the middle of a conversation without starting over. It also set the carrier-agnostic pattern: new carriers’ packages plug into the same section-based architecture. Configuration, not redesign.

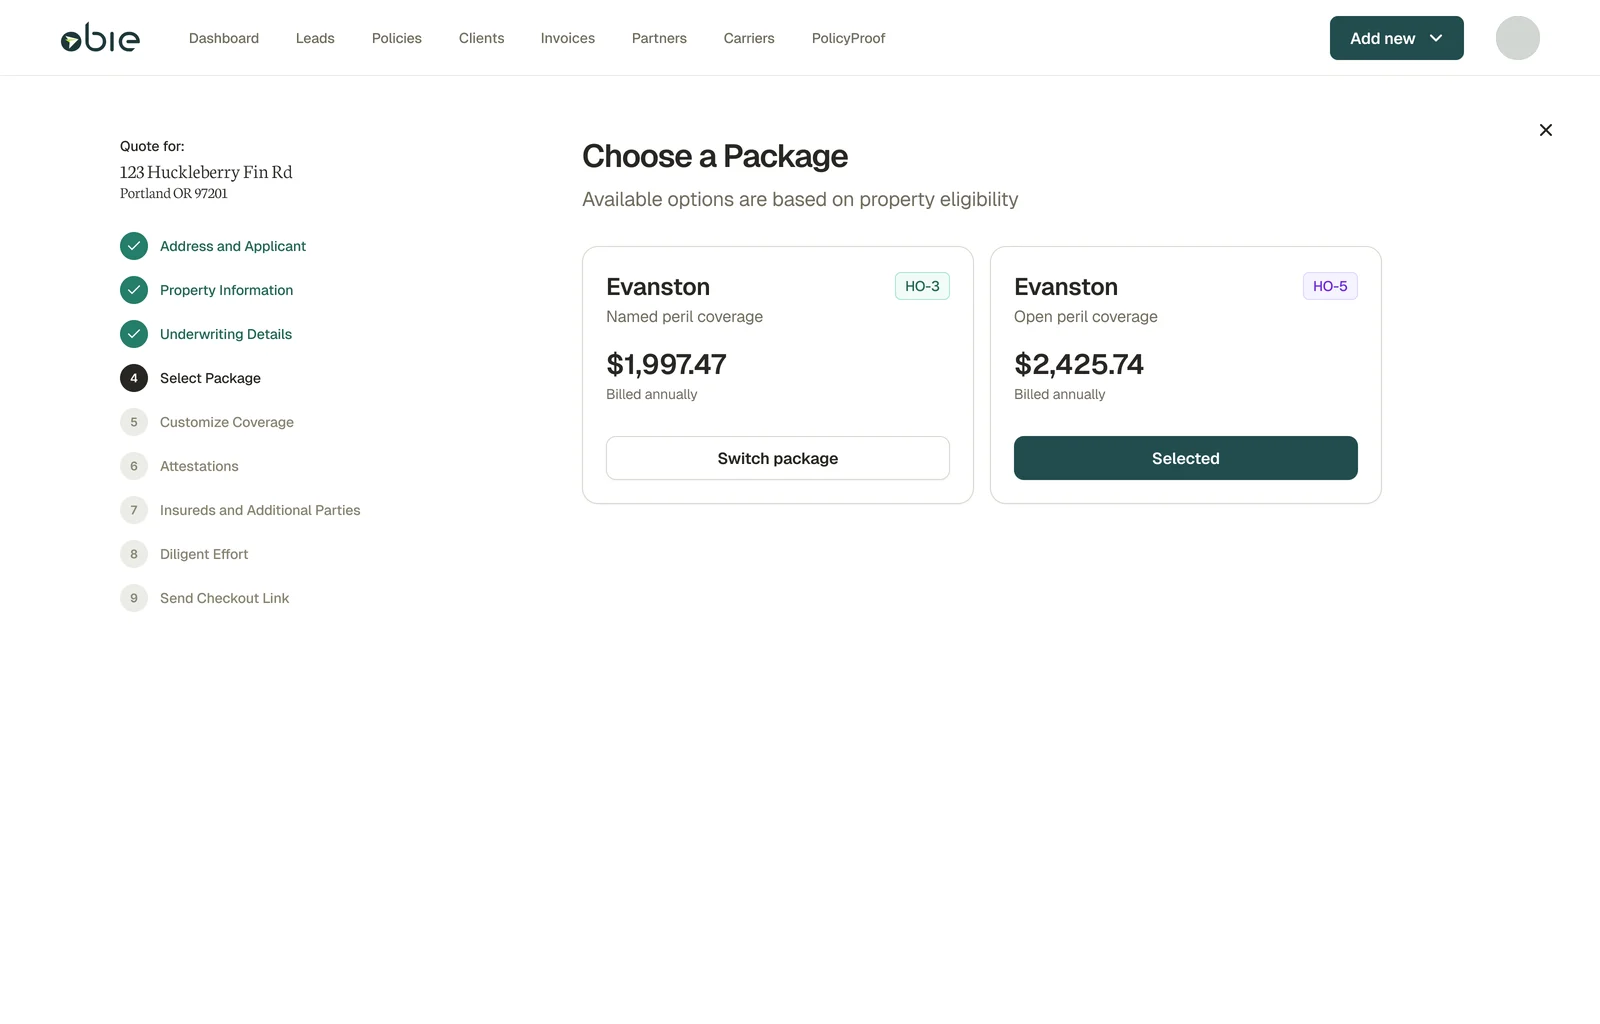
Choose a Package step: an HO-3 named-peril card and an HO-5 open-peril card side by side, each with an annual price, one selected and one with a Switch package button
The whole bet, as one button. Switch package, and the shared answers come along.

The system was drawn before the screens

Before opening Figma, I spent the first weeks in FigJam with the lead engineer, defining how state, validation and rating would behave as agents moved through the experience. Those were the decisions that would be nearly impossible to reverse once development started. We went from rough system diagrams to screen designs, then prototyped the package-switching behavior. Underwriting signed off on every question set for each package before a line of code was written.

What came out was a section-based, carrier-agnostic framework rather than a one-off homeowners flow. Questions render from carrier rules, so a new carrier plugs in without a redesigned flow. The same property and underwriting sections serve homeowners, landlord and the products after them. Agents move forward and backward freely while the system decides when validation and re-rating happen. High-impact underwriting questions surface early, and standard properties take the low-friction path.

The weeks in FigJam felt slow at the time. They’re the reason we shipped on time.

Without this architecture

  • HO-3 → Custom flow
  • HO-5 → Custom flow
  • A national carrier’s HO-3 → Custom flow
  • Future Carrier → Custom flow

Each carrier × package = unique design + engineering work

With carrier-agnostic architecture

Shared section-based framework

  • HO-3
  • HO-5
  • A national carrier’s HO-3
  • + Future carriers

New carrier = configuration, not redesign

Evolution The gap one framework had to absorb, at the customization step.

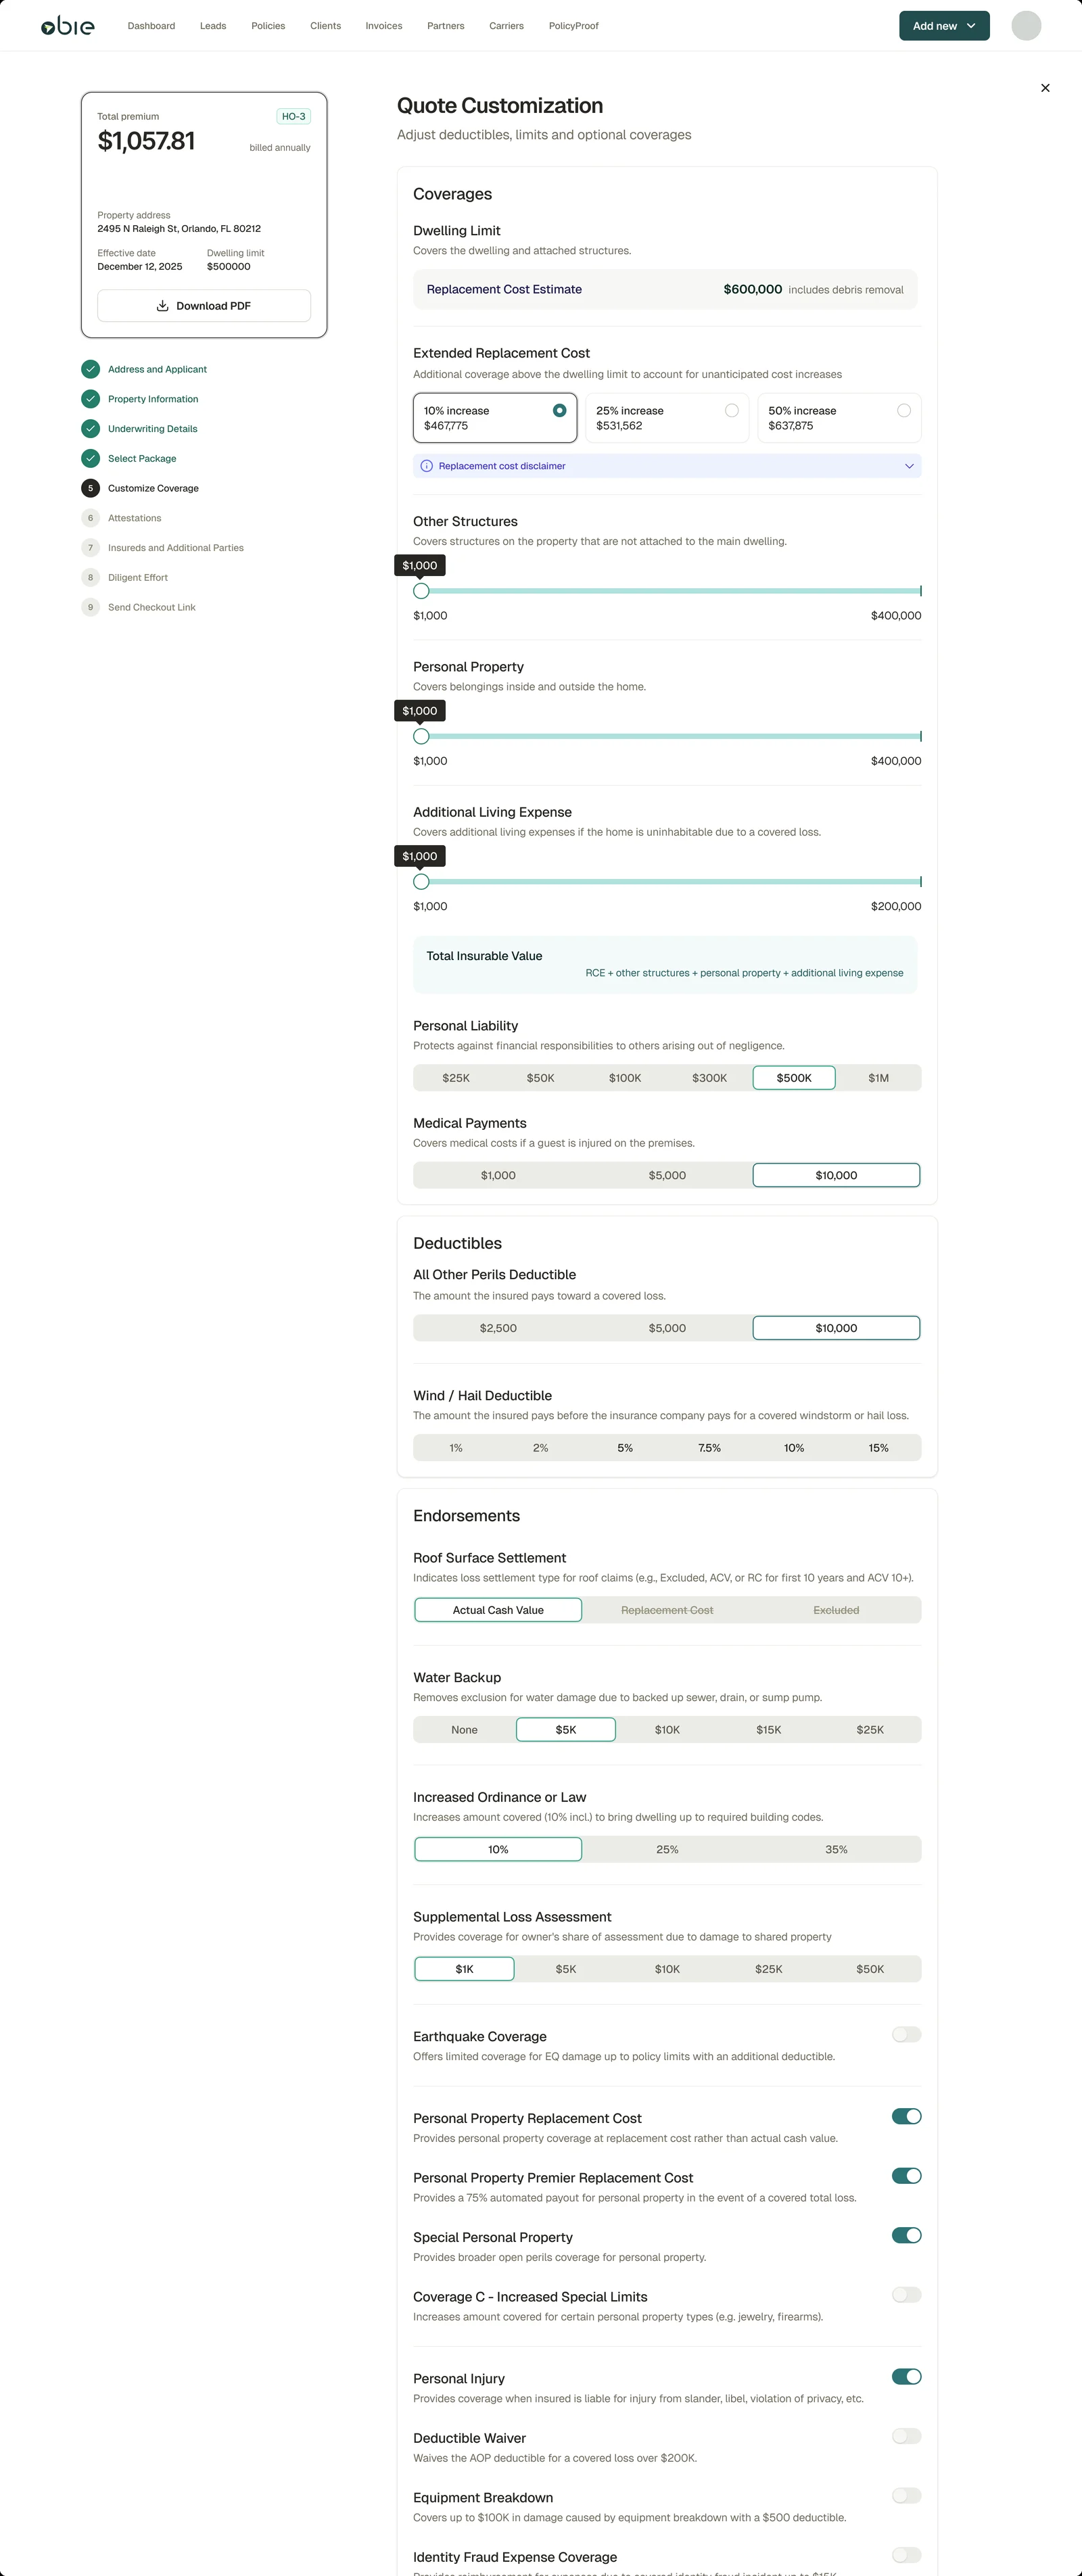
Landlord coverage customization: a short list of fixed coverages with a few sliders and a deductible picker
Landlord: a short list and a few sliders.
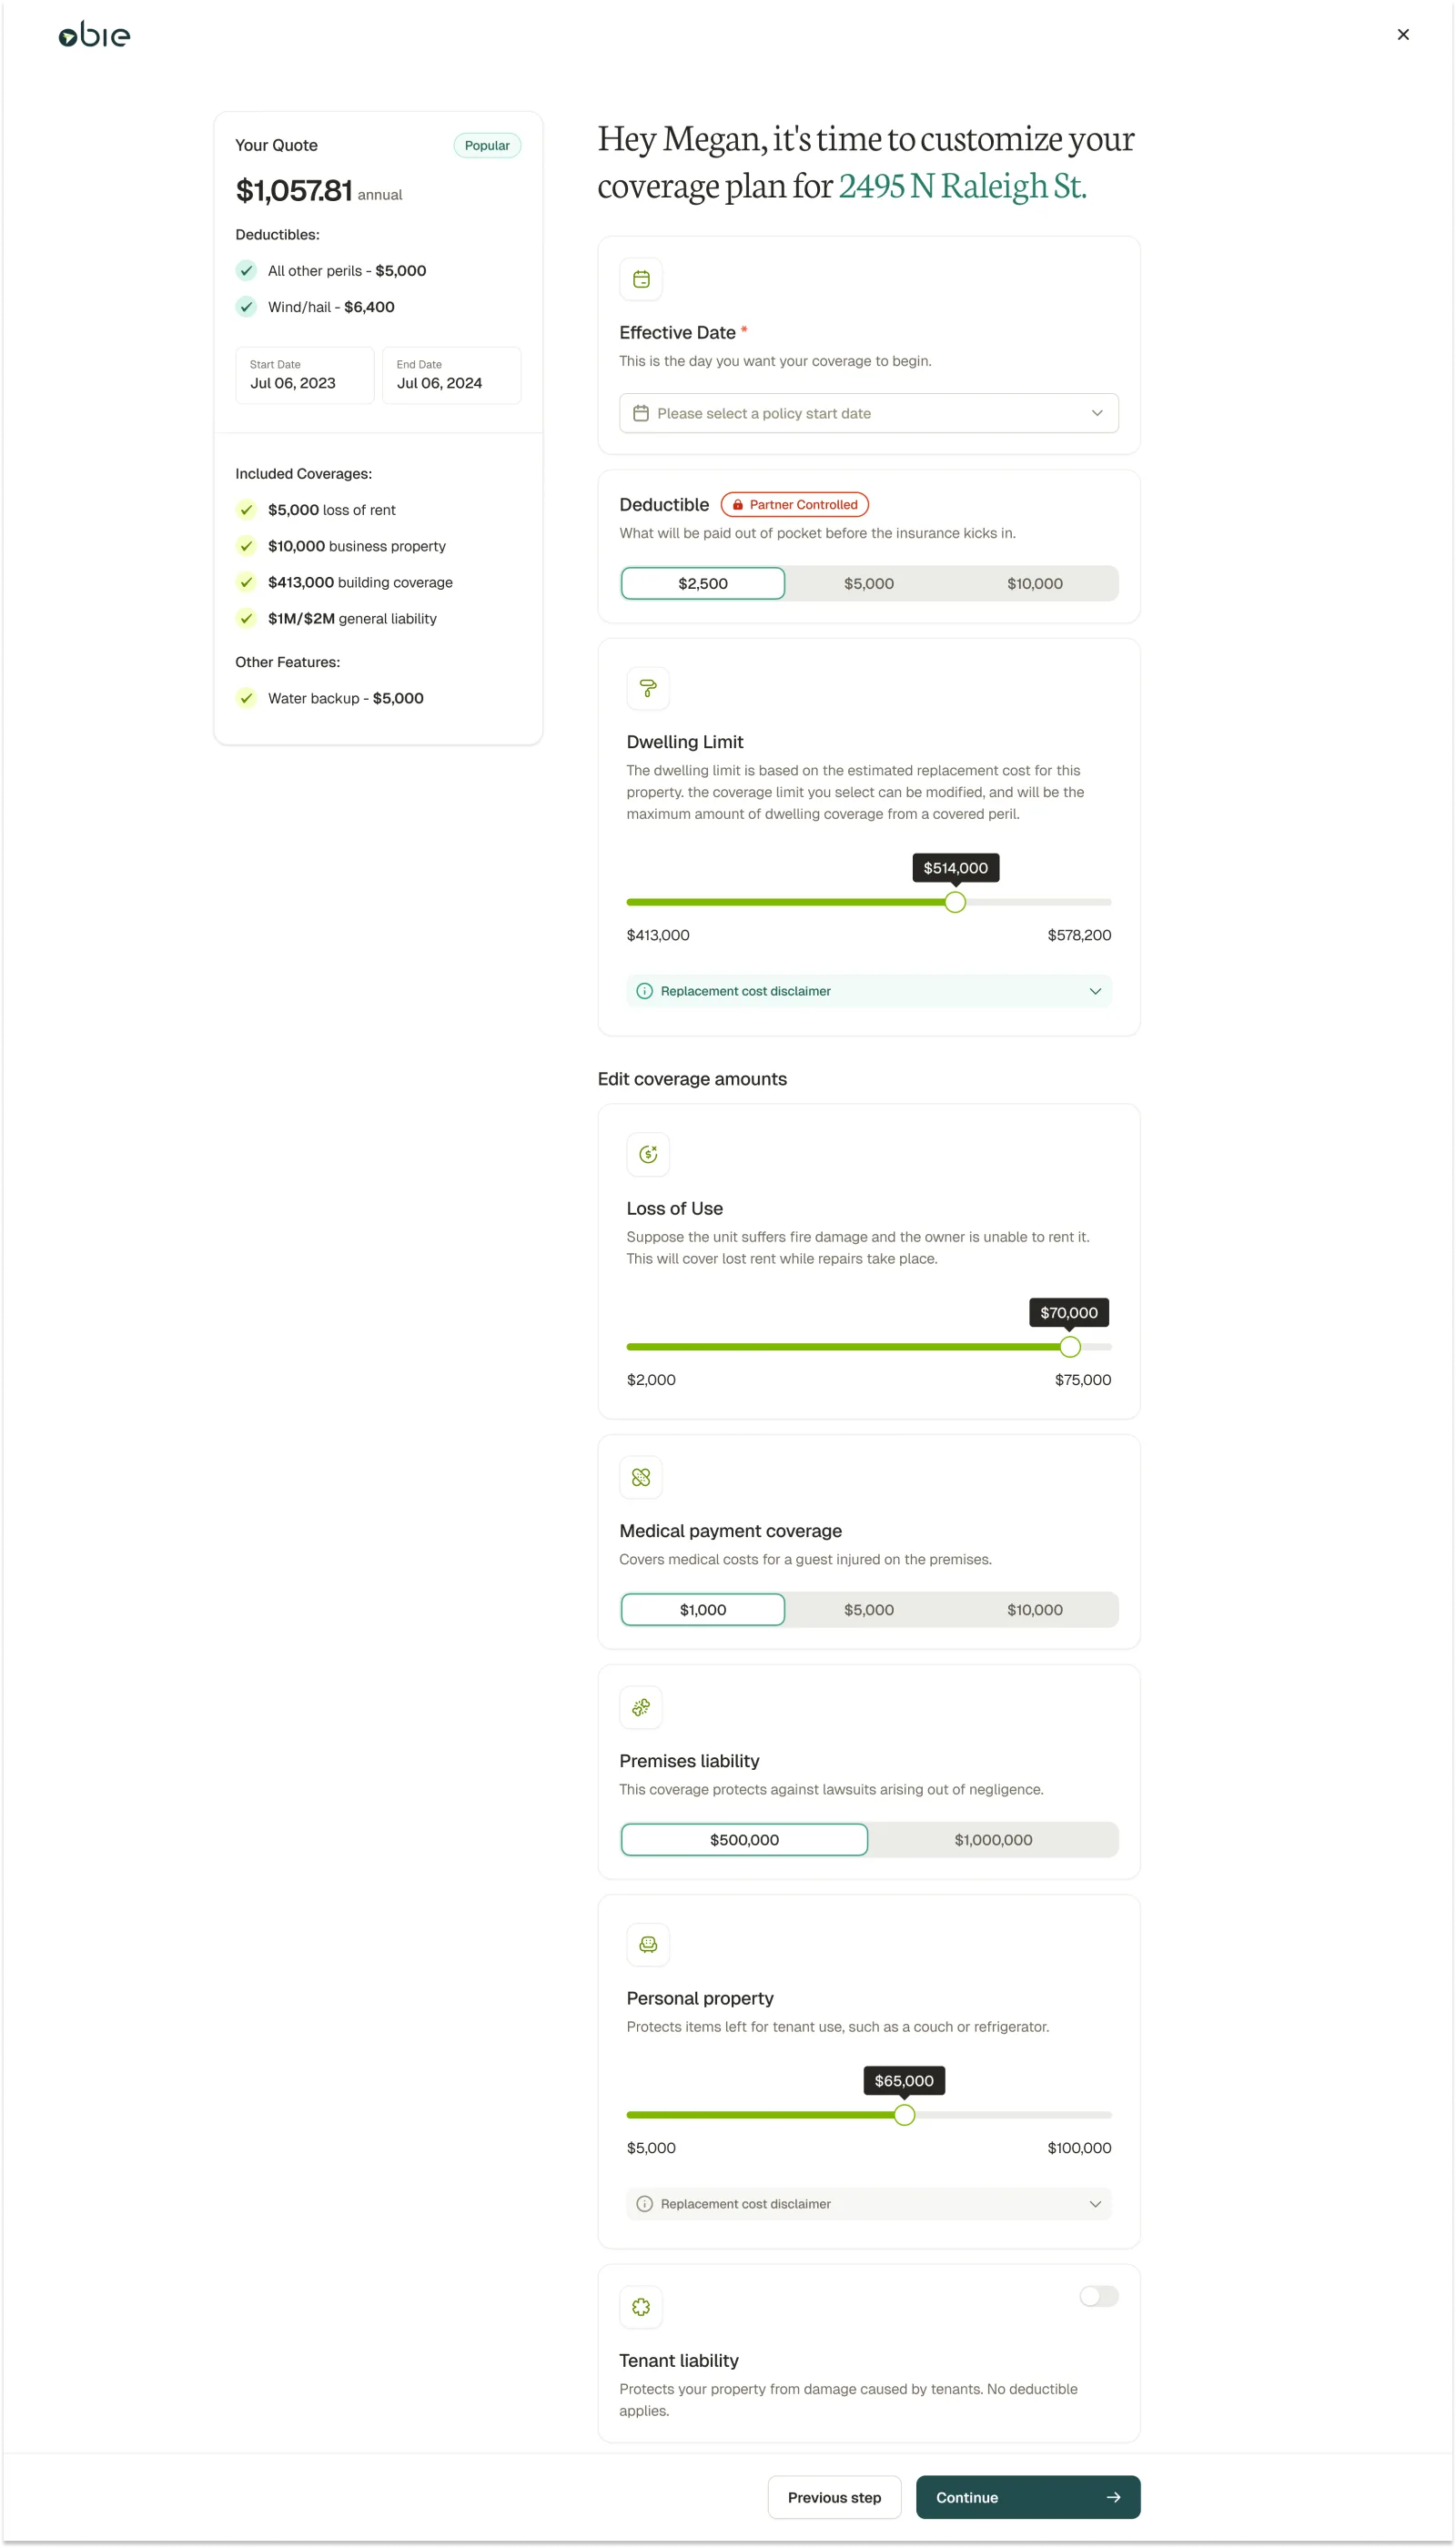
Homeowners coverage customization: full control of limits, deductibles and a long list of optional endorsements
Homeowners: every limit, every deductible, and a long list of endorsements.

April 29.

The system shipped on deadline, bind-ready on April 29, 2026: the full quoting experience, HO-3, HO-5 and HO-6 through a carrier partner, on a platform that had never handled homeowners insurance. Real agents generated real homeowners quotes that produced real policies. Validation metrics were defined before launch, and results were tracked weekly from launch: leads, quotes, binds and error sessions.

Then agents started waiting.

Launch found the seams we hadn’t hidden

The first weeks after launch exposed what the plan couldn’t: slow carrier pricing calls. And our own flow charged agents for them twice. Generating the quote PDF was tied to recalculating the premium, so agents waited for the rate, then waited again for the document.

We separated the two and gave the disabled states clear language. The PM’s weekly report credited the change by week three.

Time wasn’t the only seam. The launch window also brought a wave of defects. I sorted the ticket pile into systemic themes: patterns, not one-off bugs. The pile had a shape. After that, the error rate fell sharply within weeks.

The last miss was mine. We got the underwriting question sequencing right, but we got there through close collaboration with the Underwriting team rather than by watching agents use the product. Question ordering needed late-stage adjustments that even informal agent ride-alongs would have caught weeks earlier. In a four-month timeline, those weeks matter. I’d push for agent testing earlier.

Then the research read-out came back, blunt in a useful way: usability wasn’t the main barrier to conversion.

Where it stands

Bind-ready since April 29, 2026, on three packages and one flow. I was the sole product designer on the initiative, working with our UI designer, and in partnership with Product, Engineering and Underwriting from day one.

System Map Three packages, one flow: the branch is one step of nine. The steps as the shipped progress list names them.

  1. Step 1Address & Applicant
  2. Step 2Property Information
  3. Step 3Underwriting Details
  4. Step 4Select Package
  5. Step 5Customize Coverage
  6. Step 6Attestations
  7. Step 7Insureds & Parties
  8. Step 8Diligent Effort
  9. Step 9Send Checkout Link

Dynamic checkpoint Package branching point (HO-3 / HO-5 / HO-6)

The agent quote builder has its own case study, and Breaking the Handoff tells the process side.

Building something in this lane? Email me.